The Cultural Difference Between How Europeans and Americans Build Companies
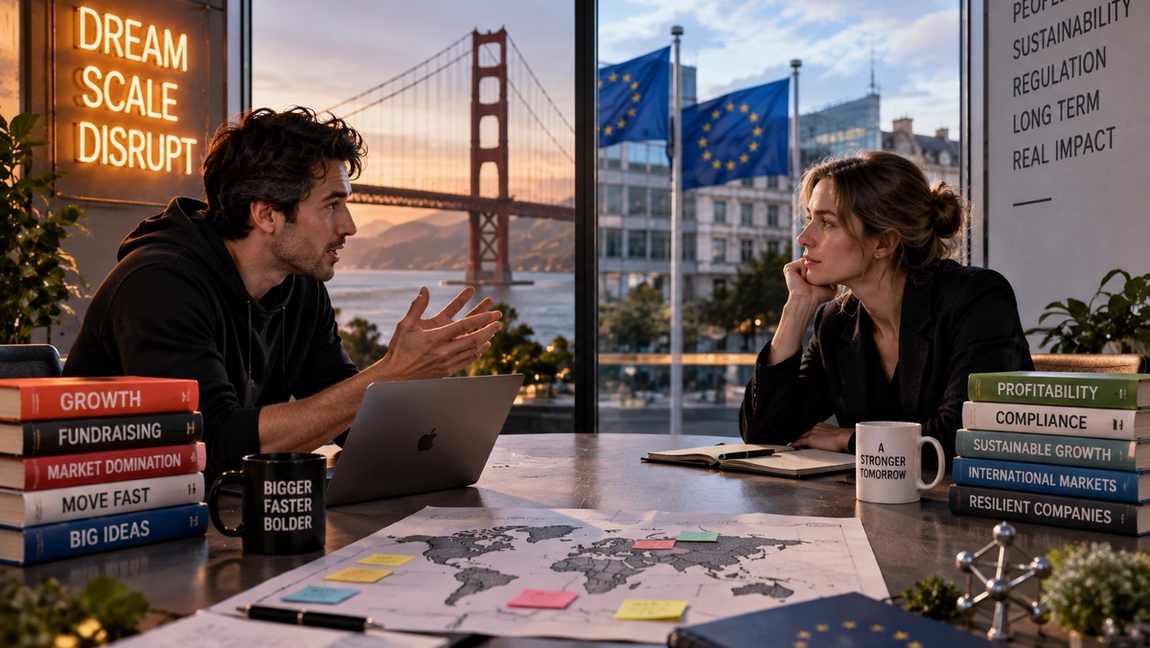
Put a European founder and an American founder in front of the same business opportunity and they may build surprisingly different companies. The American might raise a large round early, hire aggressively, talk openly about dominating the market, and prioritize speed. The European might raise less money, focus on revenue earlier, expand more cautiously, and spend longer proving the business before making enormous claims about its future.
By Aidan Mays on September 17, 2026
Getty Images
Put a European founder and an American founder in front of the same business opportunity and they may build surprisingly different companies. The American might raise a large round early, hire aggressively, talk openly about dominating the market, and prioritize speed. The European might raise less money, focus on revenue earlier, expand more cautiously, and spend longer proving the business before making enormous claims about its future.
Those are broad generalizations, of course. A Berlin AI startup can be more aggressive than a San Francisco software company, and Europe itself contains dozens of different business cultures. Building a company in Stockholm is not identical to building one in Milan, just as building in New York is not identical to building in Austin.
Still, there are structural and cultural differences between the two ecosystems. They come from the size of their markets, availability of capital, attitudes toward risk and failure, labor systems, regulation, and even the language founders use when talking about ambition. Understanding those differences helps explain why American and European startups can feel different even when they are building similar products.
American founders begin with an enormous home market
One of America’s greatest startup advantages is easy to underestimate: scale.
A founder can build in California, sell to customers in Texas, hire in New York, expand into Florida, and operate within one enormous national economy. There are differences between states, but the company is still generally working with the same language, currency, federal institutions, and broadly connected commercial market.
European founders face a different reality.
The European single market provides access to hundreds of millions of consumers, but selling across Europe can still involve different languages, tax systems, customer expectations, regulatory interpretations, employment practices, and business cultures.
A startup succeeding in Germany cannot automatically assume that its strategy will work identically in France or Italy.
This affects how founders think.
American startups can spend years becoming large domestic companies before seriously internationalizing. Many European startups need to think internationally much earlier because individual national markets are smaller.
The American advantage is easier initial scale.
The European advantage is earlier exposure to complexity.
Silicon Valley normalized enormous ambition
American startup culture, particularly Silicon Valley culture, has developed an unusually comfortable relationship with enormous claims.
Founders talk about building billion-dollar companies before they have revenue. Investors discuss markets worth hundreds of billions. Startups openly describe plans to replace established industries.
From the outside, this can sometimes sound ridiculous.
Occasionally it is.
But the cultural permission to think extremely big has consequences. If founders believe they are building a global company, they may raise more money, recruit more aggressively, enter markets faster, and make investments that would appear unreasonable for a smaller business.
European founders have historically been somewhat more restrained.
A founder saying, “We want to completely transform global banking,” may be received differently in London or Berlin than in a Silicon Valley investor meeting.
European business culture often places greater value on credibility and evidence before making extraordinary claims.
Neither approach is universally better.
American confidence can create extraordinary companies.
It can also create extraordinary bubbles.
European caution can produce disciplined businesses.
It can also cause founders to underestimate what they could build.
Americans are generally more comfortable with risk capital
The availability of venture capital changes company culture.
The United States has a substantially larger venture-capital ecosystem than Europe, particularly at later stages. American founders therefore operate in an environment where raising large amounts of private capital to pursue rapid growth has become relatively normalized.
That encourages a particular startup model.
Raise money. Hire quickly. Acquire customers. Expand geographically. Accept significant losses temporarily. Raise another round. Continue scaling.
The assumption is that if the company can capture a sufficiently valuable market, profitability can come later.
European founders have historically had less access to that scale of capital.
As a result, many European companies have been forced to pay attention to revenue and efficiency earlier.
That can produce healthier economics, but it can also slow expansion. A European company growing carefully from €5 million to €20 million in revenue may suddenly face an American competitor that has raised €200 million and is willing to spend aggressively to enter the same market.
Capital changes what founders are able to consider reasonable.
Failure carries different cultural weight
American startup culture has developed a surprisingly forgiving attitude toward entrepreneurial failure.
A founder can shut down a company, write about what went wrong, and potentially raise money for another startup a year later.
Failure can even become part of the founder’s narrative.
“I learned what not to do.”
In parts of Europe, business failure has historically carried more stigma. Bankruptcy rules, financial consequences, conservative professional cultures, and social attitudes have sometimes made entrepreneurship feel like a larger personal risk.
That difference has been changing as European startup ecosystems mature.
London, Berlin, Stockholm, Paris, Amsterdam, Tallinn, and other technology hubs increasingly contain repeat founders, investors who understand startup failure, and employees comfortable moving between young companies.
But cultural memory changes slowly.
When failure feels expensive, founders naturally behave differently.
They may raise less, hire more cautiously, and prioritize survival.
Europeans often build with regulation in mind earlier
American founders frequently encounter regulation after they begin scaling.
European founders often encounter it while designing the company.
GDPR affects data handling. Financial technology companies face complex licensing requirements. AI companies increasingly need to consider the EU AI Act. Cybersecurity companies operate within frameworks such as NIS2 and DORA. Employment protections influence hiring and restructuring.
This can frustrate founders because compliance consumes money and attention that could otherwise go toward growth.
But it also shapes products.
A European startup may build privacy controls, documentation, data governance, or regulatory workflows into the product earlier because customers already expect them.
That can become useful when selling to governments, banks, healthcare systems, and large enterprises where compliance is part of the purchasing decision.
American startups sometimes move faster because they encounter fewer constraints early.
European startups sometimes become more structurally prepared for regulated markets because they never had the option to ignore them.
Hiring reflects different ideas about employment
American startup employment culture can be extremely fluid.
Employees move frequently between companies. Equity compensation can represent a meaningful portion of compensation. Rapid hiring during growth periods may be followed by equally rapid layoffs when conditions change.
European employment systems generally provide stronger worker protections.
The exact rules differ significantly between countries, but hiring and firing can be more administratively complicated and expensive than in many parts of the United States.
That influences startup behavior.
European founders may hire more cautiously because increasing headcount represents a longer-term commitment.
American founders may be more willing to build large teams quickly because restructuring later is comparatively easier.
The American model can allow companies to respond faster.
The European model can encourage more deliberate workforce planning.
Neither eliminates bad management.
They simply create different incentives.
Americans are better at selling the future
One of Silicon Valley’s most powerful skills is storytelling.
American founders often become extremely good at explaining not only what their company currently does but what it could eventually become.
Investors are not merely buying today’s revenue. Employees are not merely joining today’s product. Customers are not simply purchasing today’s feature.
Everyone is being invited into a larger future.
European founders sometimes communicate more conservatively. They may focus heavily on product specifications, current customers, technical quality, and measurable performance.
That builds credibility.
But it can also undersell the opportunity.
A startup needs both substance and narrative.
The strongest European founders increasingly understand that storytelling is not necessarily exaggeration. It is the ability to explain why today’s small company could matter enormously tomorrow.
Europeans may have an advantage in building internationally
Because European companies encounter borders earlier, international operations can become normal surprisingly quickly.
A startup from the Netherlands might hire employees in Portugal, sell into Germany, raise investment from Britain, and operate engineering teams in Poland before reaching significant scale.
That experience develops capabilities American companies sometimes need to learn later.
Localization becomes normal. Multiple currencies become normal. Different regulatory environments become normal. Distributed teams become normal.
A company that survives Europe’s fragmentation can become unusually adaptable when expanding globally.
What initially looks like a disadvantage can therefore become training.
The two cultures are gradually borrowing from each other
The most interesting development is that the American and European startup models are becoming less distinct.
European founders are becoming more ambitious about global scale, raising larger rounds, investing more aggressively in technology, and becoming more comfortable telling enormous stories.
American startups, meanwhile, have become more conscious of capital efficiency, profitability, regulation, privacy, and sustainable growth following periods when growth-at-any-cost produced painful corrections.
Each ecosystem is learning from the other’s weaknesses.
Europe needs more of America’s comfort with ambition, risk, storytelling, and scale.
America can benefit from Europe’s emphasis on efficiency, resilience, regulation, and international complexity.
The strongest companies increasingly combine both.
The real difference is what founders are taught to optimize for
American startup culture often asks, “How big could this become?”
European startup culture has historically been more likely to ask, “Can we build this sustainably?”
Those questions lead founders toward different decisions.
One encourages speed, experimentation, capital, and enormous ambition. The other encourages discipline, evidence, efficiency, and resilience.
But the best founders eventually need to answer both.
A sustainable company without ambition may never realize its potential. An ambitious company without sustainable economics may simply burn through enormous amounts of money.
The future of European entrepreneurship may therefore not depend on copying Silicon Valley.
It may depend on taking what Silicon Valley does exceptionally well—the willingness to imagine enormous outcomes—without abandoning the qualities that have produced many of Europe’s strongest companies: patience, technical depth, international thinking, and the ability to build businesses that eventually have to work in the real world.