The Real Difference Between Seed, Series A, and Series B in Europe
Startup funding rounds can sound like levels in a game. A company raises seed funding, reaches Series A, moves to Series B, and continues through later rounds as it grows. From the outside, the main difference appears to be the amount of money involved.
By Hunter Hurley on September 17, 2026
Getty Images
Startup funding rounds can sound like levels in a game. A company raises seed funding, reaches Series A, moves to Series B, and continues through later rounds as it grows. From the outside, the main difference appears to be the amount of money involved.
But funding stages are really about evidence.
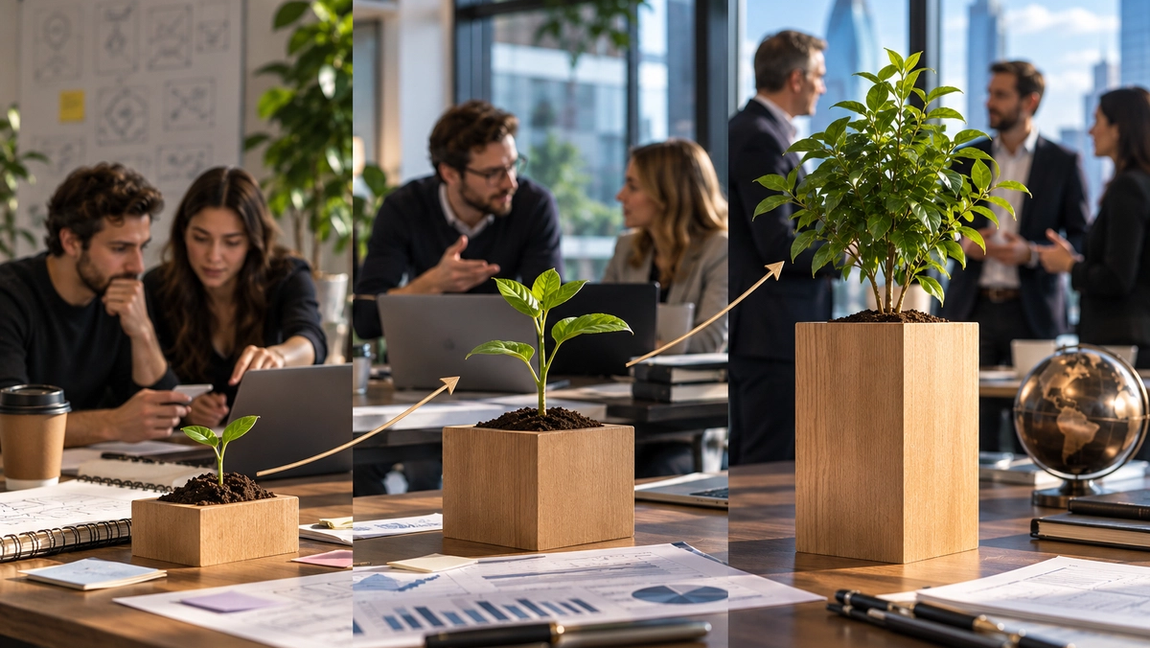
At each stage, investors expect the startup to have answered a different set of questions. Seed investors are often asking whether the idea could become a meaningful business. Series A investors want evidence that the business model is starting to work. By Series B, the central question is increasingly whether that model can be scaled.
In Europe, the exact size and expectations of each round vary by country, sector, and market conditions. A deep-tech startup in Munich may have a completely different funding journey from a consumer app in London. Still, the basic progression follows a recognizable pattern.
Seed is about proving something is there
At the seed stage, much of the company is still uncertain.
The founders may have built an early product and attracted initial users or customers, but they are usually still testing fundamental assumptions. Who is the ideal customer? Which features matter? What will people pay? Which acquisition channels work? How large could the market become?
Seed capital gives the company time to answer those questions.
The money might be used to hire the first engineers, improve the product, run customer experiments, build an early sales operation, or enter an initial market.
Investors understand that the numbers may still be small. They therefore pay particular attention to the founding team, the importance of the problem, the size of the potential opportunity, and early evidence of demand.
In Europe, seed rounds may involve angel investors, specialist seed funds, accelerators, government-backed programs, or larger VC firms with dedicated early-stage strategies.
The objective is not necessarily to produce enormous revenue immediately. It is to find enough evidence that the startup deserves to keep going.
Series A is about proving the model works
By Series A, the conversation becomes more demanding.
A company cannot rely as heavily on a compelling vision. Investors increasingly expect data showing that customers want the product and that there is a plausible way to build a large business around it.
For a software startup, investors might examine recurring revenue, customer retention, growth, sales efficiency, and how frequently customers use the product. A marketplace might be evaluated using transaction volume, repeat behavior, supply and demand dynamics, and take rate.
The exact metrics vary, but the underlying question is similar: Is there a repeatable engine here?
Product-market fit becomes central. The startup should have a clearer understanding of who its best customers are, why they buy, how they are acquired, and why they stay.
Series A funding is often used to turn something promising into a more structured company. The startup may build dedicated sales and marketing teams, hire experienced managers, strengthen operations, and expand beyond its initial customer segment or geography.
For European startups, international expansion may begin particularly early because a successful company can outgrow a smaller domestic market quickly.
Series B is about proving the company can scale
By Series B, investors generally expect much more of the uncertainty to have disappeared.
The company should already have a product people buy, a meaningful customer base, a functioning business model, and evidence that additional investment can accelerate growth.
The question shifts from “Does this work?” toward “How large can this become?”
Series B capital might fund expansion into several countries, a larger sales organization, new product lines, acquisitions, infrastructure, or significant hiring.
The company’s internal systems also become more important. A startup with 15 employees can operate informally. A company heading toward 100 or 200 employees needs clearer management, financial controls, recruitment processes, performance measurement, and organizational structure.
Investors therefore evaluate the company itself, not simply the product. Can management deploy a much larger amount of capital effectively? Can the sales process scale? Can the company enter new markets without breaking what already works?
At this stage, execution becomes as important as experimentation.
The numbers become progressively less forgiving
The type of evidence investors expect changes dramatically across these stages.
At seed, a few enthusiastic customers can be meaningful. At Series A, investors may want to see a pattern across a much larger customer base. At Series B, they want evidence that the pattern continues as the organization grows.
Revenue quality matters too.
A startup can technically generate impressive revenue while still having serious problems. Customers might leave quickly, acquisition costs could be too high, or a few large contracts might represent most of the company’s income.
Later-stage investors therefore look deeper into metrics such as retention, gross margins, customer concentration, sales efficiency, recurring revenue, and unit economics.
Growth alone is not enough. Investors increasingly want to understand what that growth costs and whether it can continue.
European geography changes the funding journey
One distinctive challenge for European startups is that scaling often means crossing national borders.
A US company may be able to grow significantly while selling into one large domestic market. A startup from Denmark, Portugal, Estonia, or Austria may need international customers relatively early to support venture-scale ambitions.
That can make the transition between funding stages more complicated.
A startup might demonstrate excellent product-market fit at home during seed but then need to prove at Series A that customers in Germany or France behave similarly. By Series B, investors may expect evidence that the company’s international expansion strategy is repeatable rather than dependent on one successful country.
Language, regulation, hiring, pricing, competition, and customer expectations can all change as the company expands.
As a result, European founders often need to prove not only that the product scales but that the business can travel.
Funding rounds are milestones, not achievements by themselves
Startup announcements can make fundraising look like success. A company raises €10 million, posts photographs of the team celebrating, and receives attention across the technology press.
But the investment itself is not the outcome.
Every funding round creates a new set of expectations. A seed round buys time to discover product-market fit. Series A capital is supposed to help build a repeatable growth engine. Series B funding should accelerate a model that has already demonstrated meaningful traction.
The larger the round, the more ambitious those expectations become.
That is the real difference between seed, Series A, and Series B. They are not simply larger piles of money. They represent different stages of certainty.
At seed, founders are proving that something might work. At Series A, they are proving that it does work. At Series B, they need to prove that it can work at a much larger scale.
Understanding that distinction helps founders raise money for the right reason: not because reaching the next letter sounds impressive, but because additional capital can genuinely move the company into its next stage of growth.